Free and independent
Your First Home calculator
Free First Home Scheme Calculator: Find out how much you could borrow and check if you’re eligible as a first-time buyer under the new government scheme.
Try it with any price
Results update as you type. Nothing is stored.
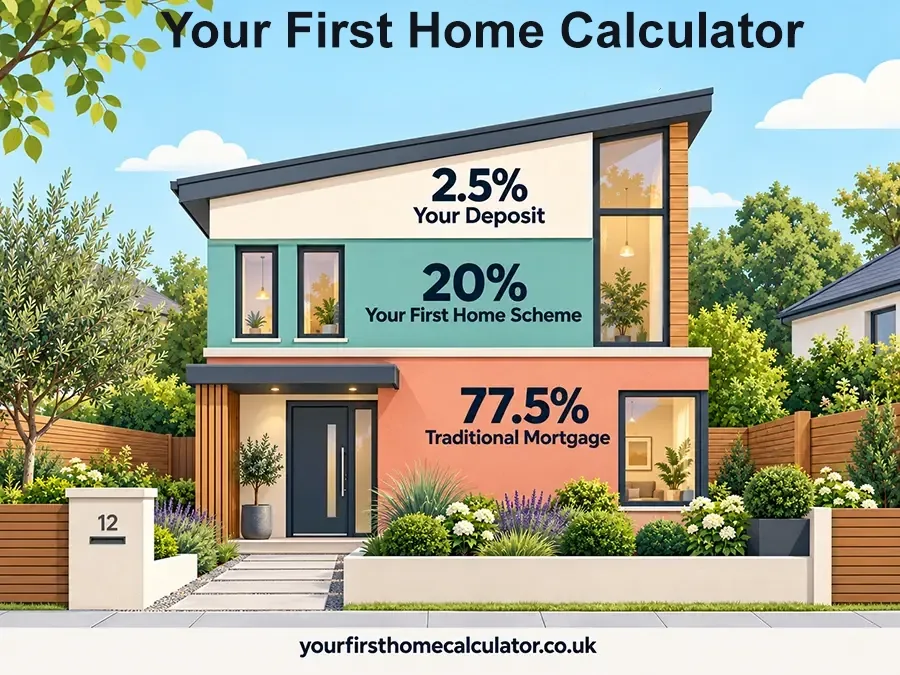
The government's new scheme lets first-time buyers in England buy a new-build home with a 2.5% deposit and a 20% government equity loan. Type a price and see what it would mean for you, next to a normal 95% mortgage.
Announced 26 September 2026. Full rules due at the Budget on 28 October 2026. We update the same day.
The scheme in 60 seconds
- You need a deposit of at least 2.5% of the price. On the £230,000 home used as the example in reports of the announcement (Rightmove's average first-time buyer price), that is £5,750. Announced, rules due at Budget
- The government lends you 20% of the price as an equity loan: it owns that share of your home's value until you pay it back. Announced, rules due at Budget
- A normal mortgage covers the remaining 77.5%, which usually means a cheaper interest rate than a 95% mortgage.
- The loan is interest-free at first. How long for, and what it costs after that, will be announced on 28 October 2026. Assumed
- New-build homes in England only, from housebuilders signed up to the scheme, for first-time buyers only, with a household income cap and local price caps still to be set. Announced, rules due at Budget
- When you sell, you are expected to repay the same percentage of the home's value at that time, not the sum you borrowed, as under Help to Buy. If prices rise, so does the repayment. Expected, detail to come
Source: MHCLG press release on GOV.UK, 26 September 2026. Badges show which figures are announced, which are confirmed in law and which are our working assumptions; the methodology page explains each one.
Start here
- What is Your First Home?
The scheme in plain English: who it is for, what the government lends you and what it costs.
- Am I eligible?
First-time buyer rules, the income cap and the price caps as far as they are known.
- How much deposit do I need?
What 2.5% means in pounds, and how long it takes to save.
- How is it different from Help to Buy?
The old scheme, the new one, and the lessons from 387,000 Help to Buy purchases.
- Compare every first-time buyer scheme
Your First Home, Shared Ownership, First Homes, Own New, 95% mortgages and the Lifetime ISA side by side.
- Shared Ownership explained
Buy a share, rent the rest. Is it worth it, and how does it compare?
Latest updates
27 September 2026
Your First Home scheme announced: what we know so farThe government announced Your First Home on 26 September 2026: a 2.5% deposit and 20% equity loan for first-time buyers on new builds in England.
Who runs this site
We are a team who have bought new houses and understand the challenges that new home buyers these days can face. We have nothing to sell you: no housebuilder, lender or government body pays for our pages or sees them before they are published. We show our sources on every page and publish how the calculators work. More about us, how we research pages and how we make money.